18/10/2026
Diamonds require appraisal. A VND 5,200 billion project in the core CBD of Ho Chi Minh City is no different — and the dossier for this asset is ready for your due diligence.
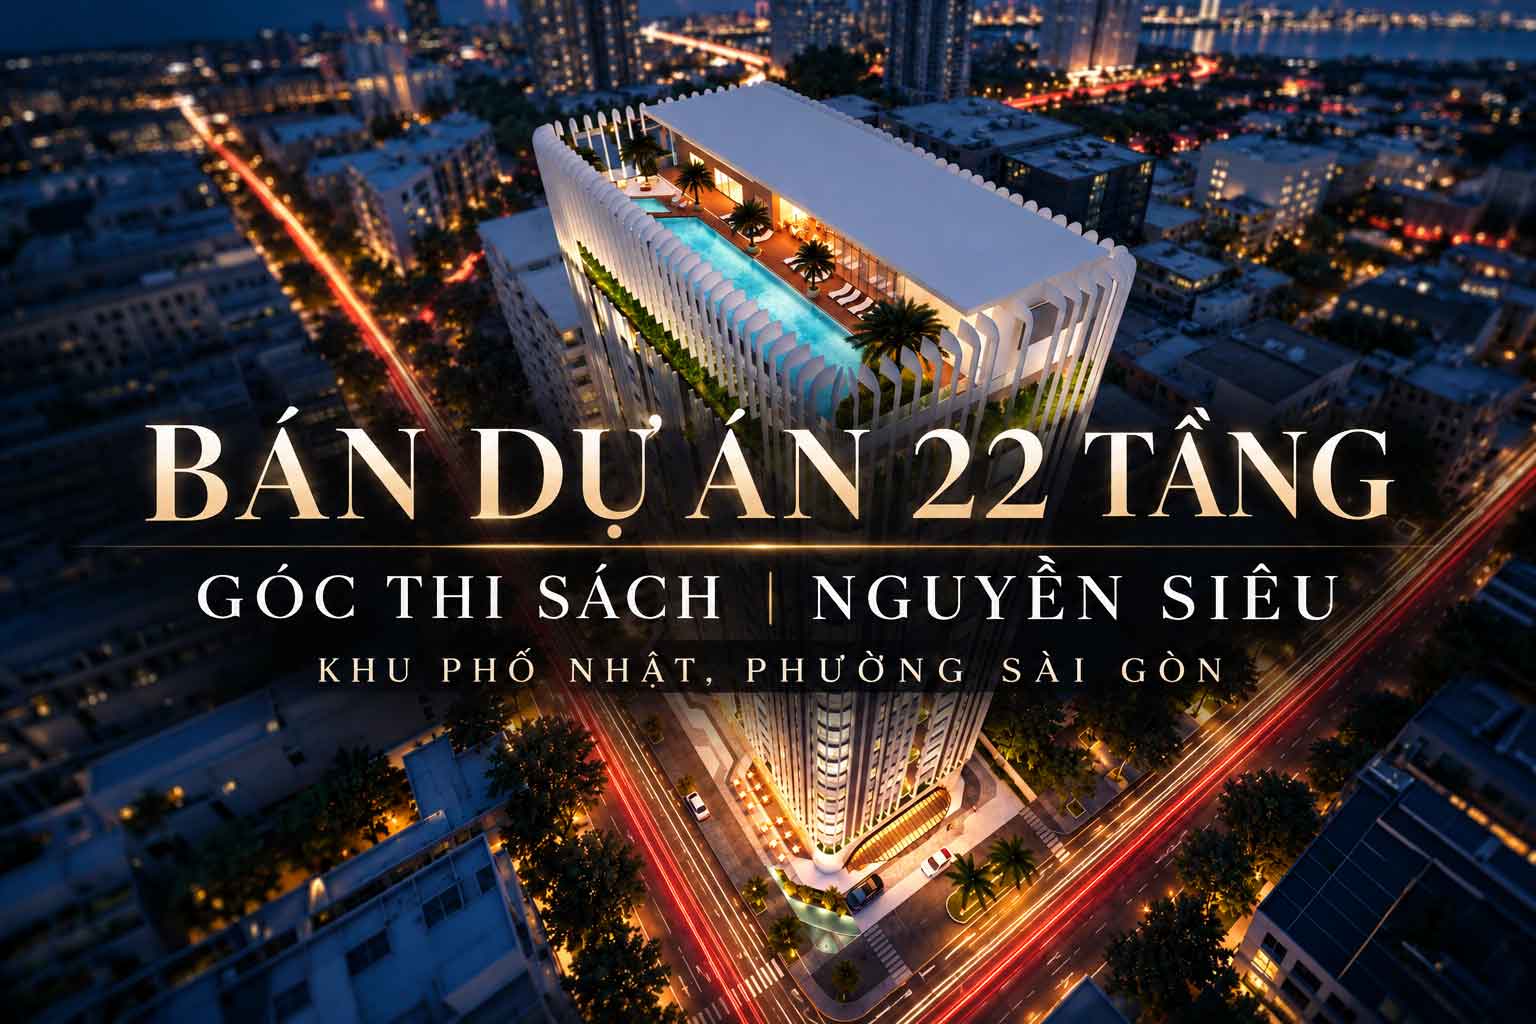
Achieve Realty VN is officially authorized to introduce the 100% equity transfer of a project enterprise owning a 3-basement, 22-story residential building located at the prime corner of Thi Sach and Nguyen Sieu streets. Positioned in the heart of Little Japan, Saigon Ward (former District 1), the project has completed its structural framework, comprising 162 long-term ownership apartments and 157 car parking spaces. Transfer price: VND 5,200 billion, inclusive of taxes and fully cleared legalities.
This brief is curated specifically for the Investment Committees of developers, institutional funds, and corporations seeking formed assets in the CBD. We present the specifications, the 2026 macroeconomic landscape, the core residential market context, pricing metrics, and a reverse-engineered financial model for you to assess if the deal fits your risk appetite. Strengths are clearly stated, and areas requiring strict appraisal are laid bare.
Quick Take: This is a residential tower with 3 basements and 22 upper floors situated on a 2,147 sqm corner plot (Thi Sach – Nguyen Sieu), Little Japan, Saigon Ward, HCMC. As of October 2026, the structural works are completed with full legal status. It features 162 long-term ownership units and is offered via a 100% corporate share transfer at VND 5,200 billion.
| Item | Specifications |
|---|---|
| Location | Corner of Thi Sach & Nguyen Sieu, core Little Japan area, Saigon Ward (former District 1), HCMC |
| Land Area | 2,147 sqm |
| Scale | 3 basements, 22 upper floors |
| Gross Floor Area (GFA) | 26,978 sqm |
| Current Status | Structural framework completed (Bare-shell) |
| Products | 162 apartments, long-term ownership |
| Parking | 157 car spaces (approx. 0.97 space/unit) |
| Legal Status | Per seller's statement: fully cleared; ready for sales launch and SPA signing |
| Transaction Type | 100% transfer of shares in the project enterprise (M&A) |
| Transfer Price | VND 5,200 billion, inclusive of taxes and legal completion (July 2026 asking price) |
| Dossier | Legal docs, blueprints, and shareholding structure available upon NDA signing |
A notable detail from the table: dividing the 26,978 sqm GFA by 162 units yields roughly 166 sqm of construction floor per unit (including basements and common areas). Such low unit density indicates a design heavily skewed towards large-format apartments, targeting the luxury or ultra-luxury segment — not a mass-market product. The actual Net Saleable Area (NSA) per unit will be verified via the master blueprints post-NDA.
Quick Take: The site simultaneously occupies three distinct value layers within HCMC's core: Little Japan, the underground section of Metro Line 1, and the boundaries of the International Financial Center. A 2,000+ sqm dual-frontage plot with cleared residential legalities in this radius is virtually irreplaceable.
The Little Japan enclave originated around Le Thanh Ton – Thai Van Lung and has since expanded to Thi Sach and Ngo Van Nam streets. According to VnExpress archives, the area hosts around 300 Japanese households and over 70 Japan-affiliated restaurants, stores, and spas. These historical figures serve as a baseline for the community's established scale.
The implication for investors is highly pragmatic: expats and Japanese families prefer residing here due to CBD office proximity and corporate shuttle access to factories in Dong Nai and Binh Duong. This constitutes a long-term, meticulous, and reliable tenant base — the exact demographic required for a luxury residential tower.
Metro Line 1 (Ben Thanh – Suoi Tien) features three underground stations: Ben Thanh, Opera House, and Ba Son. According to route descriptions, the underground track runs from the Opera House directly beneath Nguyen Sieu Street towards Ba Son. After its first year of commercial operation, the line served nearly 19 million passengers, exceeding targets by over 14%.
The exact walking distance from the project lobby to the Opera House and Ba Son station entrances will be measured during site inspections before compiling final sales materials.
Per the Decree on the International Financial Center, the designated HCMC zone covers approximately 898 hectares, encompassing parts of Saigon Ward, Ben Thanh Ward, and the Thu Thiem New Urban Area. City leaders aim to finalize the center by 2027. Consequently, Saigon Ward will be the primary destination for incoming international finance professionals — a cohort with immense purchasing and leasing power for premium apartments adjacent to their offices.
Based on the 2026 framework (referenced via Guland), the peak State land price for the Thi Sach frontage in Saigon Ward is VND 325.2 million/sqm. This is the baseline used for calculating financial obligations to the State and is significantly lower than actual market transaction values. This figure must be cross-referenced with the official HCMC Land Price Resolution.
Quick Take: The 9M-2026 picture is two-sided. Strong growth — HCMC's GRDP surged 9.06% (a 10-year high), coupled with spiking FDI. However, inflation hovering at 4.7% and mortgage rates exceeding 10%/year are forcing capital to become highly selective, prioritizing physically formed assets with clean legalities, precisely like this project.
| Indicator (9M-2026) | Value | Source |
|---|---|---|
| HCMC GRDP | ~VND 2.46 quadrillion, up 9.06% YoY | Thanh Tra |
| HCMC GRDP Q3/2026 | Up 9.86%, highest quarterly growth in 10 years | Tap chi Kinh te Tai chinh |
| HCMC share of National Economy | Approx. 23.4% | VietTimes |
| HCMC Services Sector | Up 9.27%, accounting for 51.8% of GRDP | Mekong ASEAN |
| Average CPI HCMC | Up 4.69% YoY | Mekong ASEAN |
| FDI attracted to HCMC | Over USD 17.8 billion | SGGP |
| Fixed Mortgage Rates (12-24m) | Commonly ~10.9%/year | Nha Dau Tu |
Frankly speaking: High mortgage rates slow down end-user purchasing power driven by leverage. The luxury segment is less reliant on mortgages, but project acquirers should still stress-test scenarios featuring slower-than-expected absorption rates.
Quick Take: In Q3/2026, the primary average price in pre-merger HCMC was roughly USD 4,210/sqm (~VND 110 million/sqm), per Knight Frank. At the apex, Avison Young recorded luxury segments exceeding USD 8,000/sqm and ultra-luxury nearing USD 18,000/sqm (~VND 470 million/sqm) in Q2/2026. CBD supply is overwhelmingly skewed toward luxury and ultra-luxury.
| Segment / Indicator | Primary Price Range | Period | Source |
|---|---|---|---|
| Ultra-Luxury HCMC | Approaching USD 18,000/sqm (~VND 470M/sqm) | Q2/2026 | Avison Young |
| Luxury HCMC | Over USD 8,000/sqm (Over VND 200M/sqm) | Q2/2026 | As above |
| CBD Apartments (General) | USD 3,500–5,900/sqm (VND 91–155M/sqm) | Q2/2026 | As above |
| HCMC Average (Pre-merger) | USD 4,210/sqm (~VND 110M/sqm), +3% QoQ | Q3/2026 | Knight Frank |
What does this mean for the Thi Sach – Nguyen Sieu project? Central land banks are virtually finite. New projects in Saigon Ward mainly stem from redevelopment sites, each requiring years of administrative procedures. In this context, 162 long-term ownership units ready for immediate deployment represent genuinely rare supply. However, value is only realized with correct market positioning. At the quoted M&A price, this cannot be positioned as a "standard" premium project at VND 100-150 million/sqm. The reverse financial model below illustrates why.
Quick Take: According to JLL Vietnam, residential properties continue to lead M&A volumes in H1 2026, with cash flow aggressively targeting formed assets with transparent, completed legalities. The Thi Sach – Nguyen Sieu deal matches these exact criteria.
In September 2025, UOA Group (Malaysia) completed the 100% share acquisition of VIAS Hong Ngoc Bao JSC, possessing a 2,000 sqm plot on Vo Thi Sau Street. The transfer value was roughly VND 1,775 billion (USD 68.27 million), planned for a Grade A office building with an estimated USD 120 million total investment.
| Quick Comparison | UOA – Tan Dinh (2025) | Thi Sach – Nguyen Sieu (2026) |
|---|---|---|
| Land Area | 2,000 sqm | 2,147 sqm |
| Transaction Structure | 100% Share Acquisition | 100% Share Acquisition |
| Acquisition Status | Vacant land, awaiting ground-breaking | Completed bare-shell (3 basements + 22 floors) |
| Function | Grade A Office | 162 Freehold Residential Units |
| Total GFA | ~20,000 sqm (Planned) | 26,978 sqm (Built bare-shell) |
| Transaction Value | ~VND 1,775 billion | VND 5,200 billion |
| Per Sqm Metric | ~VND 89 million/sqm | ~VND 193 million/sqm |
These two transactions belong to different asset classes and cannot be compared directly. The premium of the Thi Sach project must be justified by three factors: the sunk cost of the existing bare-shell structure, the commercial value of long-term residential sales rights, and the massive time savings in legal clearances and basement construction. The buyer should independently appraise each component.
Quick Take: VND 5,200 billion equates to approximately VND 2.42 billion per sqm of land, VND 193 million per sqm of GFA, or VND 32.1 billion per apartment unit (inclusive of parking spaces and common areas). This translates to roughly USD 203 million at the central exchange rate of ~25,610 VND/USD (early September 2026).
| Conversion Metric | Calculation | Result |
|---|---|---|
| By Land Area | 5,200 bil ÷ 2,147 sqm | ~VND 2.42 billion/sqm |
| By Gross Floor Area | 5,200 bil ÷ 26,978 sqm | ~VND 193 million/sqm |
| By Apartment Unit | 5,200 bil ÷ 162 units | ~VND 32.1 billion/unit |
| By USD Equivalent | 5,200 bil ÷ 25,610 | ~USD 203 million |
*Exchange rate referenced from the State Bank's central rate as of Sept 3, 2026. Parties should fix the exchange rate upon SPA signing.
Quick Take: Merely to recoup the acquisition cost, assuming the Net Saleable Area (NSA) falls between 14,000–18,000 sqm, the average selling price must hit VND 290–370 million/sqm (approx. USD 11,300–14,500/sqm), excluding fit-out and SG&A costs. Therefore, the project MUST be positioned in the ultra-luxury or branded residence tier to generate a margin.
We strongly urge Investment Committees to scrutinize this section. Every fund will run this model internally; we are placing it on the table upfront.
| Sensitivity Analysis: Gross Revenue minus Acquisition Cost (VND Billions) | ||||
|---|---|---|---|---|
| Assumed NSA | Breakeven Price | Sell at VND 350M/sqm (~$13.7k) | Sell at VND 450M/sqm (~$17.6k) | Sell at VND 550M/sqm (~$21.5k) |
| 14,000 sqm | ~371M/sqm | −300 | +1,100 | +2,500 |
| 16,000 sqm | ~325M/sqm | +400 | +2,000 | +3,600 |
| 18,000 sqm | ~289M/sqm | +1,100 | +2,900 | +4,700 |
*The positive figures represent the remaining buffer to cover completion costs, sales expenses, financing, and ultimately, net profit.
Quick Take: Acquiring 100% of shares means inheriting the entire enterprise and all associated liabilities. Four critical pillars demand strict due diligence: land/project legalities, hidden financial liabilities, structural integrity of the bare-shell, and sales launch compliance under current laws. "Fully cleared legalities" is the seller's claim — the buyer's legal team must verify every document.
Quick Take: The asset is best suited for developers or funds with robust equity, proven capability in executing ultra-luxury/branded products, and a medium-to-long-term holding horizon. It is unsuitable for highly leveraged, short-term speculative flipping.
| Investor Profile | Why it fits | Key Considerations |
|---|---|---|
| Domestic Luxury Developers | Possess existing sales teams, UHNWI databases; bypasses years of legal groundwork. | Profit margins depend heavily on executing top-tier pricing (see matrix). |
| Japanese Funds & Conglomerates | Situated natively in Little Japan; historical precedent of Japanese capital acquiring 100% project entities. | Managing the 30% foreign ownership quota; FDI regulatory hurdles. |
| Regional RE Funds (SG, MY, KR) | Formed CBD asset aligns perfectly with 2026 M&A trends described by JLL. | Requires clear exit structuring; FX (currency) risks. |
| Family Offices / Long-term Holders | Can retain inventory for expat leasing, capturing long-term CBD land appreciation. | Short-term rental yields typically lag behind the cost of capital. |
| Hospitality / Branded Residence Operators (JVs) | Location meets elite criteria for the branded residence model. | Brand licensing fees and rigid technical/design compliance. |
Self-test for the Investment Committee: If the sales cycle is delayed by 12–18 months, can our capital structure absorb the carrying cost? If the answer is yes, this deal strongly warrants signing an NDA to review the dossier.
Where is the project located?
At the dual-frontage corner of Thi Sach and Nguyen Sieu streets, inside Little Japan, Saigon Ward (former District 1), HCMC. It sits within the boundaries of the International Financial Center.
What is the transaction structure?
A 100% share transfer of the enterprise owning the project (M&A). The buyer assumes full control of the entity, the asset, and all associated rights and obligations.
What is the asking price?
VND 5,200 billion (July 2026 pricing), stated to include taxes and completed legalities. This equates to approximately USD 203 million.
What is the construction status?
The structural bare-shell is fully topped out, encompassing 3 basements and 22 upper floors with a total GFA of 26,978 sqm.
How many units are there, and what is the tenure?
162 residential apartments featuring long-term ownership, plus 157 car parking spaces.
When can sales be launched?
The seller indicates the project is ready for immediate sales launch and SPA (Sales and Purchase Agreement) execution. Exact timing depends on the buyer’s legal due diligence and compliance with the Real Estate Business Law 2023.
Can foreigners purchase apartments in this project?
Under current housing regulations, foreigners can own apartments subject to a maximum quota (typically 30% of total units in a condominium). Specific project eligibility must be verified by legal counsel.
How can we access the legal dossier?
The legal dossier, master blueprints, and corporate shareholding structure will be provided strictly after a Non-Disclosure Agreement (NDA) is executed with the authorized seller.
Achieve Realty VN facilitates direct engagement between qualified investors and the authorized transferring party. The process is streamlined into four steps:
We exclusively collaborate with bona fide investors and enforce strict two-way confidentiality. Trust executes the deal — especially in a multi-trillion VND transaction.